SV Investment nears 6.6x return as T&E Korea IPO sees high demand
T&E Korea, a high-speed turbomachinery specialist expanding into hydrogen fuel cell equipment, has secured a 1253.39-to-1 subscription ratio during its public offering. The successful IPO is expected to drive significant valuation gains for early investor SV Investment.
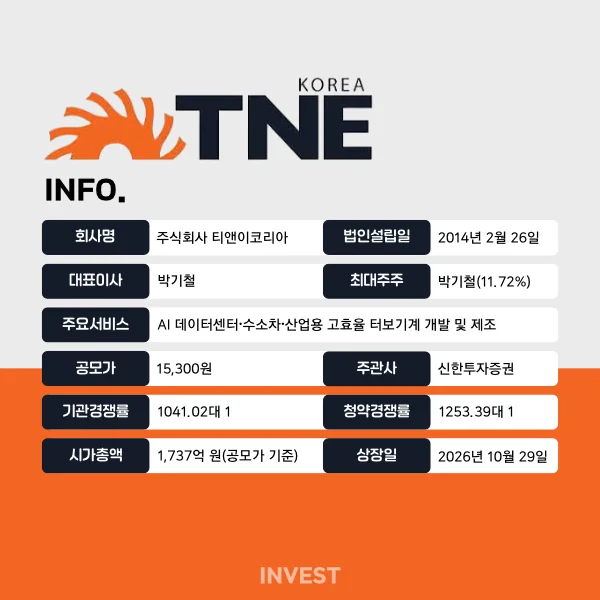
T&E Korea is set to list on the KOSDAQ Market on the 29th following a successful IPO that saw general investor competition reach 1253.39-to-1. Early investor SV Investment could see its 1.5 billion won investment grow to nearly 9.9 billion won as the company expands into AI data center power equipment.
Rising power demand for AI data centers has fueled a successful initial public offering (IPO) for T&E Korea, a specialist in high-speed turbomachinery. Investor sentiment has been bolstered by the company's expansion from traditional water treatment and industrial turbomachinery into hydrogen fuel cell power generation equipment, alongside its successful transition to operating profit in the first half of this year.
During the public subscription for general investors held from the 20th to the 21st, T&E Korea recorded a competition ratio of 1253.39-to-1, with approximately 5.7536 trillion won in deposits collected.
The company is issuing a total of 2.4 million new shares in this offering. The final offering price was set at 15,300 won, the top of the target range (12,600–15,300 won). This results in total offering proceeds of 36.7 billion won, with an expected market capitalization of approximately 173.7 billion won based on the total number of shares to be listed (11,351,096 shares).
The offering also drew high interest during the demand forecasting stage for institutional investors held from the 7th to the 14th. A total of 2,274 domestic and international institutions participated, resulting in a competition ratio of 1041.02-to-1. Regarding the requested prices, 99.76% of the total volume was requested at or above the top of the band, while only three institutions requested prices below the top of the band. The mandatory holding commitment ratio for institutional investors was recorded at 29.52% based on requested volume, with the 15-day commitment accounting for the largest portion.
SV Investment's stake value rises 6.6 times... Initial floating supply at 31%
With the finalization of the offering price, the stake value for early investor SV Investment has increased significantly. In July 2019, SV Investment invested 1.5 billion won in T&E Korea through the "SV Korea-China Culture-ICT Convergence Fund." While the company's valuation was approximately 10 billion won at that time, it rose to approximately 60 billion won during a pre-IPO in February this year.
The fund holds 644,560 shares, representing a 5.68% stake after the offering. Based on the offering price, the value of this stake is nearly 9.9 billion won, which is approximately 6.6 times the original investment. This represents an evaluation gain of 8.4 billion won. However, there was no sale of existing shares in this offering, and actual investment recovery will depend on the stock price and the timing of sales following the listing.
Immediately after listing, the volume of shares available for distribution is 3,551,856 shares, or 31.27% of the total shares. The largest shareholder holds approximately 31% of the shares and has set a 36-month lock-up period. In contrast, 160,589 shares held by SV Investment can be sold immediately after listing, while the remainder will be released from mandatory holding requirements over a period of 1 to 3 months.
The significant evaluation gains for existing investors and the phased release of mandatory holdings could act as a burden on the stock price in the early stages of trading. T&E Korea is scheduled to list on the KOSDAQ Market on the 29th, with Shinhan Securities serving as the lead manager.
T&E Korea Business Analysis
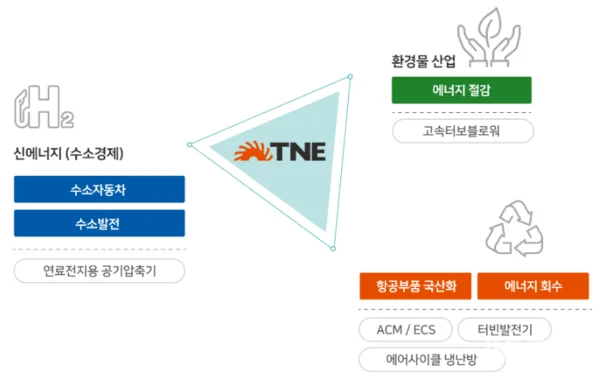
T&E Korea is a company that develops and manufactures industrial turbomachinery based on high-speed motor and oil-free bearing technologies. It is characterized by its air bearing technology, which supports rotating bodies without lubrication to reduce friction and energy loss. The company is expanding its business scope from existing water treatment and industrial turboblowers to power generation equipment for AI data centers and components for hydrogen vehicles.
A core growth driver is the air blower for Solid Oxide Fuel Cell (SOFC) power generation. This device supplies oxygen to fuel cells and is utilized in the self-generation facilities of data centers. In the first half of this year, sales reached approximately 7.6 billion won, accounting for 36.1% of total revenue. This is a significant increase from 18.8% last year, making it the company's largest revenue item. Conversely, the proportion of water treatment turboblowers decreased from 39.5% in 2024 to 17.6% in the first half of this year.
Cooperation with global customers is also leading to mass production. Following technical discussions that began in 2018 with a US-based SOFC manufacturer (Company A), the two parties entered into a mass production supply contract in July 2024 after joint development. The company also supplies core components for air compressors for hydrogen vehicles to the domestic finished vehicle supply chain and plans to begin mass production of components for next-generation hydrogen vehicles starting in 2028. Air blowers for linear generators are also being supplied overseas.
However, concentration on specific customers is a risk factor. The revenue share of the top three customers rose from 20.4% in 2023 to 54.0% in the first half of this year. In particular, a single US SOFC manufacturer (Company A) accounts for approximately 37% of total revenue. This means the impact of order reductions or changes in investment plans by major customers on performance has increased.
There is also uncertainty regarding the front-end market and the supply chain. Even if power demand for AI data centers increases, demand for SOFC could slow if alternative power generation methods, such as gas turbines or Small Modular Reactors (SMR), expand. The hydrogen vehicle business is influenced by charging infrastructure and government support policies, and there is a risk of supply disruptions due to export controls and price fluctuations regarding rare earth raw materials used in high-speed motors, which have a high dependency on China.
T&E Korea Performance and Fund Usage Plan
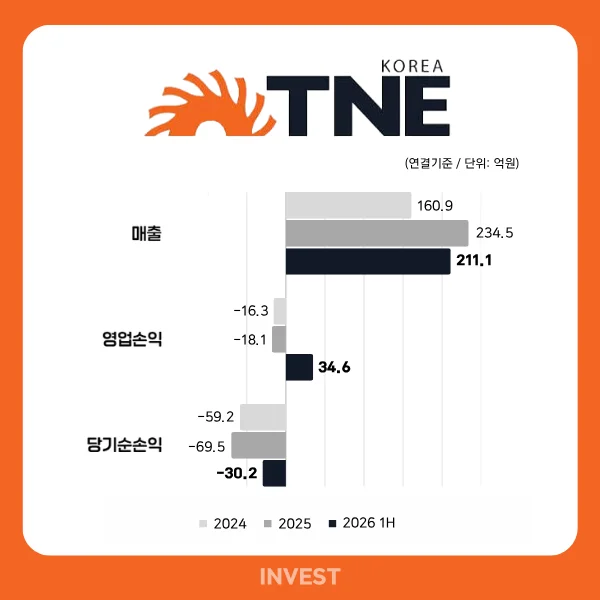
T&E Korea succeeded in turning an operating profit along with an increase in revenue in the first half of this year. Based on the consolidated financial statements, revenue for the first half reached 21.1 billion won, reaching 90% of last year's annual revenue. The operating deficit that continued for the past two years also turned into a surplus, recording an operating profit of 3.5 billion won. The gross profit margin rose from 25.1% last year to 38.5% in the first half of this year, as revenue expansion and a decrease in the cost ratio supported improved profitability.
However, it could not escape a net loss. The net loss for the first half of this year was 3 billion won, affected by a 6.4 billion won loss on valuation of derivatives related to convertible redeemable preferred shares. Excluding this valuation loss, the profit before income tax was a 3.4 billion won surplus. All 2,148,720 convertible redeemable preferred shares were converted into common shares during the first half, causing the related liabilities to vanish.
Cash flow from operating activities remains a burden factor. While it recorded a net inflow of 500 million won in 2024, it turned into a net outflow of 5.6 billion won last year, and a 600 million won outflow occurred in the first half of this year as well. In particular, accounts receivable and other current receivables more than doubled from 6.6 billion won at the end of last year to 13.5 billion won at the end of June this year.
The financial structure improved due to the conversion of preferred shares. Total equity, which was minus 5.1 billion won at the end of last year, increased to 15.3 billion won at the end of June this year, and total liabilities decreased from 39.9 billion won to 24.7 billion won. However, current liabilities amount to 20.4 billion won, and total borrowings reach 15.9 billion won.
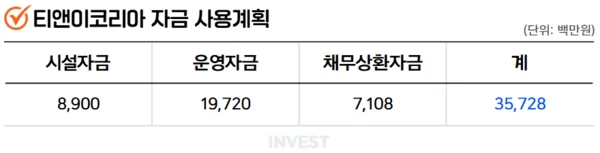
T&E Korea plans to invest the public offering funds raised through this IPO into expanding production facilities, research and development, and repaying borrowings. The total public offering amount is 36.7 billion won, and the net proceeds excluding issuance costs are approximately 35.7 billion won. Specifically, 19.7 billion won is allocated to operating funds, 8.9 billion won to facility funds, and 7.1 billion won to debt repayment.
Facility investment will focus on the expansion of the Osong plant in Cheongju, Chungbuk in 2027. 4 billion won will be invested in constructing a new factory to respond to increased production, 2.9 billion won in machinery and facility equipment, and 2 billion won in factory automation. Through this, the company plans to expand the production capacity of air blowers for power generation and recirculation blowers, and increase production efficiency using automated equipment.
The operating funds, which account for the largest portion, will be used for research and development and manpower expansion. 13.4 billion won has been allocated to ordinary research and development expenses for researchers, and investments will also be made in developing new products such as air compressors for hydrogen vehicles, ultra-low temperature turbo chillers, and devices for heat pumps. 2.5 billion won is scheduled to be used for recruiting manufacturing personnel following the increase in production volume.
Of the 7.1 billion won allocated to debt repayment, 2.7 billion won will be prioritized for amounts maturing this year, and the remainder is planned to be executed sequentially through 2030.
Covers IPO for INVEST NEWS GLOBAL, and also writes about Government.
Comments 0
Comments are currently disabled.