[IPO Preparation] Solis, Luxco, and Celtrix Kick Off KOSDAQ Entry via 'SPAC Mergers'
Solis, Luxco, and Celtrix have begun their journey toward KOSDAQ listing through mergers with Special Purpose Acquisition Companies (SPACs).
Solis, Luxco, and Celtrix have simultaneously kicked off their entry into the KOSDAQ market through mergers with Special Purpose Acquisition Companies (SPACs). The move is drawing attention as all three companies passed their preliminary listing examinations on the same day and chose the common path of merger-based listing rather than the typical public offering method.
The KOSDAQ Market Division of the Korea Exchange announced on the 28th that it approved the preliminary listing examinations for Solis, Luxco, and Celtrix following deliberations and resolutions by the KOSDAQ Market Listing Committee. Accordingly, the three companies plan to formally pursue KOSDAQ listing through subsequent procedures, such as general shareholder meetings to approve the mergers. Market interest is expected to focus on the future merger processes, corporate value calculation, and growth potential after listing.
[Solis] Semiconductor and Secondary Battery Process Utility
Solis is pursuing its KOSDAQ entry through a merger with Hanwha Plus No. 5 Special Purpose Acquisition Company. In a structure where Solis survives and Hanwha Plus No. 5 Special Purpose Acquisition Company is dissolved, the merger is expected to be finalized following subsequent procedures such as approval at the shareholders' meetings of both companies. The merger value for Solis is 11,157 won per share, and the merger date is scheduled for February 16 of next year.
Established in 2018, Solis is a process utility specialist primarily focused on Central Supply Systems (CCSS) for high-purity chemicals used in semiconductor and display processes. The company possesses turnkey capabilities, performing everything from design to manufacturing, installation, and commissioning. Based on these process utility technologies, it has expanded its business scope into the secondary battery field, supplying waste NMP (N-Methylpyrrolidone) recovery and purification equipment as well as electrolyte supply systems (CESS).
Expanding business in North America is a core growth point for Solis. Following its registration as a partner for LG Energy Solution, the company has expanded its overseas revenue base by participating in battery production hub projects in Canada and the United States. In line with this, it is strengthening its local business foundation by establishing 100% owned subsidiaries in Canada in 2024 and the United States in 2025.
The semiconductor business is a new growth engine for Solis. The strategy is to expand the business scope from the existing CCSS to Slurry Supply Systems (SSS) for Chemical Mechanical Polishing (CMP) processes. This is a move to diversify the business structure, which is currently centered on secondary batteries, into semiconductors.
However, the dependence on the North American secondary battery business is a risk factor. Due to the nature of project-based businesses, the scale of revenue and the timing of recognition may vary depending on the customer's facility investment and construction schedules. In the future, whether the company can steadily continue securing orders in North America while increasing the revenue contribution of the semiconductor business will determine its growth sustainability.
◆ Solis Performance
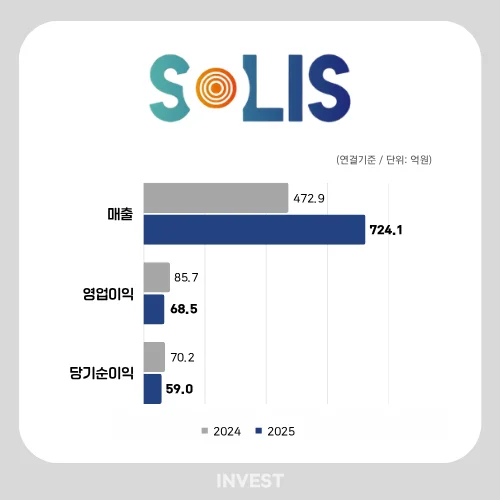
Last year, the company saw simultaneous external growth and a slowdown in profitability. On a consolidated basis, revenue increased by 53.1% compared to the previous year, while operating profit decreased by 20.1% and net profit decreased by 16.0%. As the burden of selling, general, and administrative expenses grew larger than the increase in gross profit, the rapid external growth did not lead to an increase in profit.
The expansion of the North American subsidiary's scale was also notable. While the revenue of the Canadian subsidiary more than doubled compared to the previous year, it recorded a net loss of approximately 2 billion won. The U.S. subsidiary, established last year, also recorded a deficit. As the North American business is growing rapidly, the company faces the task of improving the profitability of its local subsidiaries.
While the financial structure has improved, contract assets have increased significantly. Due to an increase in capital and a decrease in debt, the debt ratio dropped from 282.3% to 170.6%, and current and non-current contract assets increased significantly to 27.2 billion won at the end of last year from the previous year (4.9 billion won). Since revenue is recognized according to the project progress rate, a difference may occur between the timing of contract asset recognition and when they are actually collected as cash.
Cash flow showed a trend opposite to external growth. Cash flow from operating activities turned into a net outflow of 2.7 billion won last year, and cash and cash equivalents also decreased from 6.1 billion won in the previous year to 3.5 billion won.
[Luxco] Manufacturing of Switchboards for Ships and Land
Luxco signed a merger agreement with IBKS No. 24 SPAC last June. Upon completion of the merger, Luxco will be listed on the KOSDAQ as the surviving entity, and IBKS No. 24 SPAC will be dissolved. The merger value for Luxco is 7,739 won per share, and the merger date is scheduled for December 5 of this year. The SPAC public offering funds are planned to be used for production facilities and research and development (R&D) investments.
Established in 1998, Luxco is a power equipment specialist primarily focused on switchboards for ships and land. It has production bases in Ulsan and Busan and has built a business scope ranging from switchboard design and manufacturing to power control devices.
Shipboard switchboards, which are closely linked to the shipbuilding industry, are Luxco's main business. Switchboards are devices that stably supply and control power within a ship to each piece of equipment. Based on the technology and production capabilities accumulated in the shipbuilding sector, the company has expanded its product lineup to include switchboards for land industries and plants.
Recently, it has been expanding its business scope into the renewable energy field. Based on existing power equipment technology, it has also entered energy businesses such as solar power generation systems. However, as the main business is influenced by the shipbuilding and facility investment industry conditions, the demand for ship and industrial switchboards may vary depending on the customer's ship construction and facility investment schedules.
◆ Luxco Performance
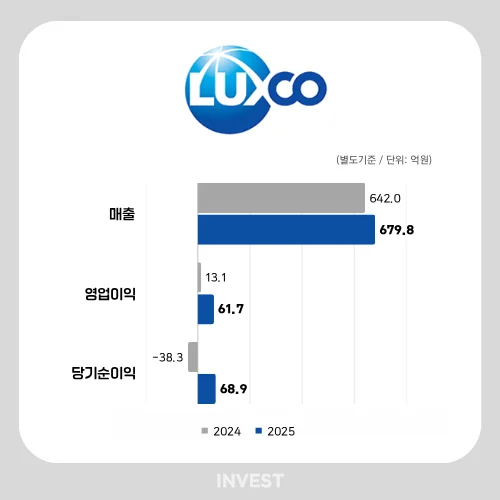
While Luxco's revenue last year increased by only 5.9% compared to the previous year, its operating profit grew nearly fivefold, from 1.3 billion won to 6.2 billion won. The expansion of gross profit, combined with a reduction in impairment losses on accounts receivable from 1.3 billion won to 400 million won, contributed to the improvement in operating profit.
Net profit also turned from a 3.8 billion won deficit the previous year to a 6.9 billion won surplus. Amid the significant increase in operating profit, financial profit and loss also turned from a 5.7 billion won deficit to a 700 million won surplus, widening the improvement in net profit.
The financial structure has also become more stable. As financial liabilities related to convertible bonds disappeared and cash increased, net debt decreased from 15 billion won the previous year to 2.9 billion won last year. Accordingly, the capital procurement ratio calculated by the company dropped from 77.2% to 20.7%.
Cash flow also improved. While cash flow from financing activities recorded a net outflow of 4.6 billion won due to the impact of repaying financial liabilities related to convertible bonds, cash flow from operating activities turned from a net outflow of 1.5 billion won the previous year to a net inflow of 10.4 billion won last year. As a result, cash and cash equivalents at the end of the period increased from 1.8 billion won to 8.3 billion won.
[Celtrix] Food Safety and Animal Diagnosis Solutions
Celtrix is pursuing a KOSDAQ listing through a merger with IBKS No. 25 SPAC. A merger agreement was signed last June, and the process will proceed in a manner where Celtrix survives and IBKS No. 25 SPAC is dissolved. Based on current disclosures, the merger date is scheduled for December 10.
Established in 2019, Celtrix is a specialized diagnostic company engaged in both food safety and animal diagnosis. In the food safety field, it provides rapid testing systems for residual harmful substances, and in the animal diagnosis field, it provides diagnostic kits and pet diagnostic testing services. The company has expanded its business scope from antigen/antibody development to diagnostic product manufacturing and testing services.
A characteristic of its business structure is the expansion of diagnostic technology secured in food safety into animal diagnosis. In the food sector, it supplies testing systems to identify residual antibiotics and harmful substances remaining in milk and other products, and in the animal sector, it provides diagnostic products for industrial animals and testing services for pets. According to the company, it holds approximately a 90% share in the domestic milk testing kit market.
The pet diagnosis business has expanded its scale through mergers and acquisitions. Following the absorption merger of the pet diagnostic testing agency Korea Vet Lab in October 2024, Celtrix absorbed Bionet in July last year. Korea Vet Lab provides specialized tests such as blood tests and PCR/genetic tests that are difficult for animal hospitals to perform themselves. By adding testing services to product sales, the company has effectively broadened the scope of its diagnostic business.
◆ Celtrix Performance
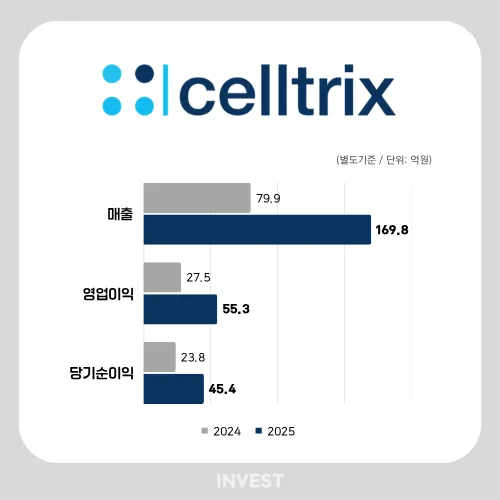
Celtrix's revenue last year was 17 billion won, more than doubling compared to the previous year. During the same period, operating profit was 5.5 billion won and net profit was 4.5 billion won, increasing by 101.0% and 91.2%, respectively. In particular, the operating profit margin was 32.6%, maintaining profitability in the 30% range even as revenue more than doubled.
However, last year's performance also reflects the effects of business combinations. Since it underwent two absorption mergers, it is difficult to interpret the increase in revenue solely as organic growth of the existing business.
The financial structure remained at a stable level. While total assets at the end of last year increased to 25.6 billion won from 20.6 billion won the previous year, total liabilities remained at a similar level to the previous year's 4.1 billion won, at 4 billion won. As total equity increased from 16.5 billion won to 21.6 billion won, the debt ratio decreased from 24.7% to 18.5%.
Cash flow from operating activities increased approximately twofold from 3.4 billion won the previous year to 6.6 billion won last year. On the other hand, there was a net outflow of 3.4 billion won in investing activities, which was mostly accounted for by the net cash outflow due to business combinations (2.9 billion won). In financing activities, there was also a net outflow of 1.1 billion won due to the impact of dividend payments, etc. However, as the cash inflow from operating activities exceeded this, cash and cash equivalents at the end of the period increased from 3.5 billion won to 5.5 billion won.
Covers IPO for INVEST NEWS GLOBAL, and also writes about Government.
Comments 0
Comments are currently disabled.