[IPO] 'First Exception to Dual Listing' Duksan Navcours heads to KOSDAQ riding K-Defense exports... General subscription ratio 333:1
Duksan Navcours, the first company to be granted an exception to the dual listing prohibition…
Duksan Navcours, which is preparing to enter the KOSDAQ as the first exception to the dual listing prohibition, has completed its public offering amid high interest from institutional investors. The offering price was determined at the top of the target band, and following the demand forecasting, it continued a favorable trend in the general subscription. However, after listing, variables remain such as the floating supply, existing shareholder selling pressure, and shareholder value issues due to the dual listing.
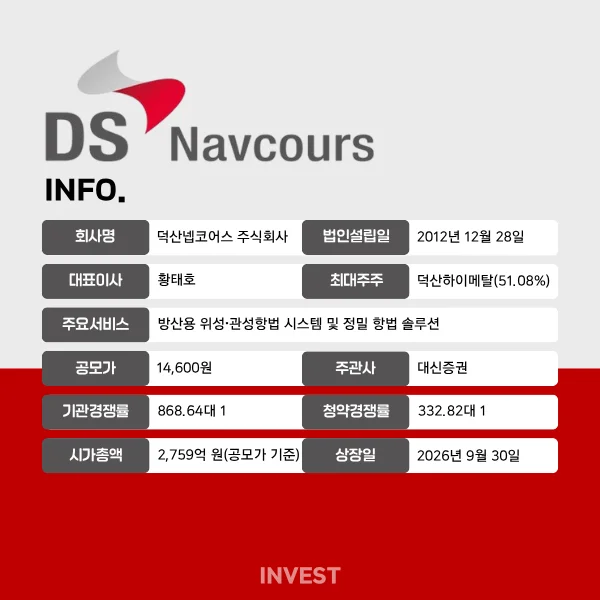
In the general public subscription for Duksan Navcours held on the 16th and 17th, a total of 132,911 subscriptions were received, with a final competition ratio of 332.82 to 1 and deposits reaching 1.8222 trillion won. This offering, with Daishin Securities as the lead manager, was conducted through the issuance of 3 million new shares, with an offering amount of 43.8 billion won and an expected market capitalization of approximately 275.6 billion won.
In the previously conducted institutional demand forecasting, 2,269 domestic and foreign institutions participated, recording a competition ratio of 868.64 to 1. 97.13% of the requested quantity proposed prices at or above the top of the target band (12,400~14,600 won), and accordingly, the offering price was finalized at 14,600 won. While institutional acceptance of the price was high, the ratio of applications for mandatory holding commitments during the demand forecasting was only 4.05%.
In the final allocation process, as the institutional mandatory holding volume increased, the floatable supply immediately after listing decreased compared to the original expectation. The floatable supply immediately after listing is 6,289,515 shares, which is 33.29% of the total planned shares to be listed. Among these, the existing shareholder volume reaches 4,577,904 shares (24.23%), so not only the selling by IPO investors but also whether the existing shareholders' volume actually enters the market could act as a variable in the early stages of listing.
Another issue is the parent company's shareholder value problem due to the dual listing. Duksan Navcours is a subsidiary of Duksan Hi-Metal, and this listing is the first case exceptionally permitted after the prohibition of the dual listing principle. Duksan Hi-Metal has proposed a shareholder protection plan to provide 150,000 shares of Duksan Navcours as a dividend in kind to general shareholders. However, the possibility of changes in the equity value of parent company shareholders due to the subsidiary's listing is also listed as an investment risk in the registration statement.
Duksan Navcours Business Analysis
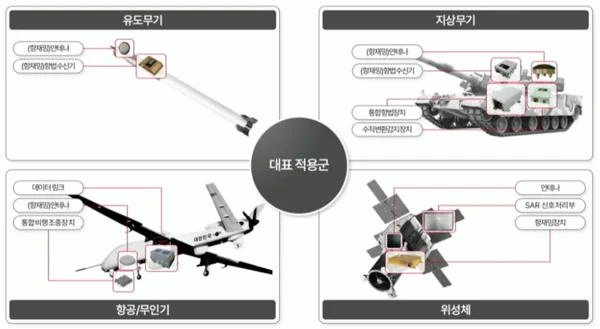
Duksan Navcours is a company that develops and manufactures precision navigation and anti-jamming solutions for defense. The core technology is PNT (Positioning, Navigation, Timing), which is a technology that accurately identifies the position, direction, and time information of moving objects such as military vehicles, missiles, aircraft, and drones, and supports navigation. By combining this with anti-jamming technology, it maintains navigation functions even in environments where satellite navigation signals such as GPS receive radio interference.
In the defense electronic components market, the government and the military are the end users, and actual product procurement is carried out through the Defense Acquisition Program Administration or large system integrators that win projects from each military branch. Unlike general civilian electronic components, technical reliability, quality assurance, security, and system compatibility are important. From the weapon system development stage to the adoption of products, test evaluation and securing references are required, and since once applied, components are used for a long time, it is not easy for new companies to enter the existing supply chain.
Within this market structure, Duksan Navcours has expanded its product lineup to include satellite navigation devices, anti-jamming devices, integrated navigation systems (EGI), data links, electronic warfare equipment, seekers, and antennas/distributors. In particular, integrated navigation technology aims to provide navigation information even in environments without satellite signals, and it is expanding its application range to various platforms such as tanks, armored vehicles, and unmanned vehicles.
As overseas exports of K-Defense expand recently, the market is also widening for related component companies. Duksan Navcours' technology is applied to major domestic weapon systems such as the K9 Self-Propelled Howitzer, K2 Black Panther, and Chunmoo. If the export of finished weapon systems increases, an expansion in the supply of related navigation devices and electronic equipment can also be expected.
Looking at the actual customer composition, transactions with major domestic defense companies are notable. Based on 2025 revenue, Hanwha Aerospace accounted for 34%, LIG Defense & Aerospace accounted for 33%, and Hyundai Rotem accounted for 15%. Combined, these three account for 82% of total revenue, with representative domestic system integrators forming the main customer group.
However, such customer concentration is also a risk. Since revenue for defense electronic components is generated according to the development and mass production schedules of weapon systems, performance fluctuations may occur depending on the orders and production schedules of specific system integrators. The company also explained that due to the characteristics of the defense and aerospace industry, the timing of orders and revenue recognition may vary depending on government budgets, policies, and project schedules.
The market Duksan Navcours looks toward does not stop at defense. Following the supply of navigation devices applied to launch vehicles and satellites, it is also participating in businesses related to the Korean Positioning Navigation Timing (KPS) system. In the aviation field, it is also developing integrated navigation systems for manned and unmanned platforms and unmanned aerial vehicle data link technology. It is showing a pattern of expanding the navigation and anti-jamming technology accumulated in defense to aerospace and drones.
Duksan Navcours Performance and Fund Usage Plan
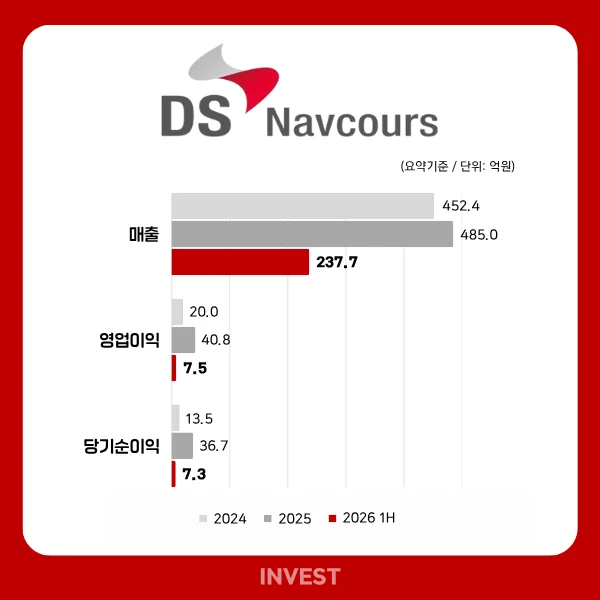
Duksan Navcours' performance showed a trend of rapid recovery from a low point in 2023. As revenue increased significantly in 2024, operating profit and net profit turned to a surplus, and in 2025, operating profit expanded further along with revenue growth. In addition to the increasing demand for navigation and anti-jamming due to the expansion of K-Defense exports, the enhancement of development and mass production capabilities through the expansion of testing facilities influenced external growth and profitability improvement.
In particular, it is notable that in 2025, operating profit increased by a larger margin than revenue. While revenue only increased by 7.2% year-on-year to 48.5 billion won, operating profit more than doubled to 4.1 billion won, raising the operating profit margin from the 4% range to the 8% range. The effect of the cost-to-sales ratio decreasing along with revenue expansion led to improved profitability.
In the first half of 2026, revenue growth and profit increase diverged. First-half revenue increased to 23.8 billion won compared to the same period last year, but operating profit decreased to 800 million won. However, since the structure is such that the inspection and delivery schedules of defense projects affect the timing of revenue recognition, it is too early to judge annual profitability based solely on the first half. As the order backlog at the end of June also stands at 55.7 billion won, exceeding 90% of this year's expected revenue, the recognition of revenue from order volumes in the second half and whether the profit margin recovers will determine the performance trend.
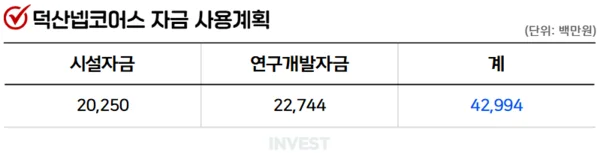
Duksan Navcours plans to invest the net proceeds of approximately 43 billion won secured through the public offering into expanding factories and facilities and into research and development (R&D).
Out of the total funds, 20.3 billion won will be used to expand production infrastructure. Specifically, 8.8 billion won will be invested in securing land near the Daejeon headquarters and existing manufacturing facilities, and 11.5 billion won will be invested in expanding production and testing facilities. As the space and production capacity (CAPA) of the current production and development infrastructure are limited, this is an investment to respond to the mass production volumes of major defense businesses.
The remaining 22.7 billion won will be invested in R&D to focus on internalizing core technologies. In particular, investment will be concentrated in 2027–2028, and it will be used to develop technologies such as digital ASIC, sensor fusion, and data links. ASIC is a core technology that implements product miniaturization and functional integration by integrating anti-jamming functions and other features into a single semiconductor. The plan is to secure a technological foundation that can expand the scope of application to UAM, autonomous driving, and robots, along with the advancement of existing defense products.
Comments 0
Comments are currently disabled.