[Management Dispute] Hoban Group's stake in Hanjin KAL exceeds 20%... Only 0.42%p away from Cho Won-tae's side, will it escalate into a management dispute?
Hoban Group's stake in Hanjin KAL, the parent company of Korean Air, has reached 20.15%…
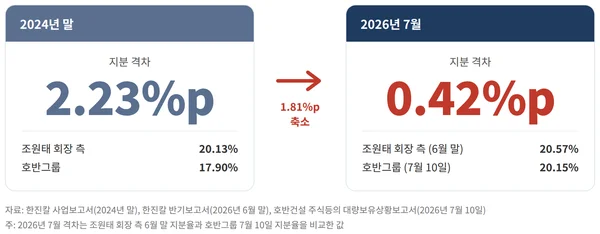
Market attention is focusing on the possibility of changes in the governance structure of Hanjin KAL, the parent company of Korean Air. Currently, the largest shareholder of Hanjin KAL is Chairman Cho Won-tae of Hanjin Group and his specially related parties, with a stake of 20.57% based on the semi-annual report. Hoban Group, the second-largest shareholder, holds a 20.15% stake according to the large-scale holding report in July. The gap between the two sides is only 0.42 percentage points, and if Hoban injects additional capital, the largest shareholder of Korean Air could change.
While the Hoban side officially maintains the position of "simple investment," the stock market is not accepting this at face value. The fact that Hoban played a key role in a management dispute with LS in the past adds weight to these suspicions. In some parts of the market, expectations and concerns about the possibility of a "second Korea Zinc incident" are being raised simultaneously.
Hoban's share acquisition over 4 years... Stake gap narrows from 2.23%p to 0.42%p
There are several reasons why the market does not view Hoban's share acquisition as a simple investment. Most notably, the history of Hoban steadily expanding its stake for about four years has had a significant impact.
The timing when Hoban emerged in earnest as the second-largest shareholder of Hanjin KAL was April 2022. At that time, as the private equity fund KCGI, which was engaged in a fierce management dispute with Chairman Cho Won-tae, declared its exit, Hoban acquired the 13.97% stake (9.4 million shares) at 60,000 won per share, totaling 564 billion won. Since then, Hoban has shown active movements, such as purchasing additional shares held by Pan Ocean and continuously increasing its stake by mobilizing affiliates. These moves can be interpreted as an intention to participate in management beyond simple investment.
Hanjin KAL, a 'scarce stock' with 25% floating volume; stock price volatility to rise if stake competition ignites
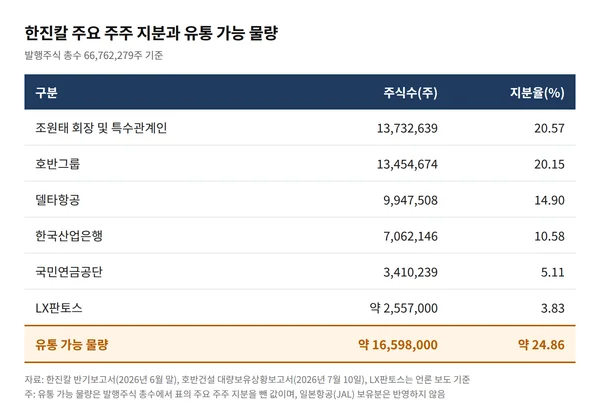
According to the June semi-annual report, the total number of issued shares of Hanjin KAL is approximately 66.77 million shares. Excluding the friendly shares of Chairman Cho Won-tae's side, Hoban's stake, and other investors' stakes, the shares actually circulating in the market account for only about 25% of the total.
This "scarce structure" with limited floating shares can act as a detonator that explodes the stock price if a dispute occurs. The recent management dispute at Korea Zinc, which shook the capital market, is a representative example. In a situation where there are almost no floating shares available for purchase, if both sides engage in a stake competition, the number of floating shares will decrease further, and as a result, stock price volatility may expand irrationally.
Hanjin KAL is a company whose stock price has reacted sensitively to share fluctuation issues in the past. In May 2025, it recorded upper limits for two consecutive days immediately after the announcement of Hoban's stake expansion, and in December of the same year, the stock price surged 20.8% in a single day solely due to speculation about Hoban's financing. Previously, the stock price also rose significantly in a short period as a management dispute between siblings broke out.
Looking at the current shareholding structure, the defensive line of Chairman Cho Won-tae's side appears quite solid. If the stake of Chairman Cho's family (20.57%) is combined with Delta Air Lines (14.90%), Korea Development Bank (10.58%), and LX Pantos (3.83%), the friendly stake ratio reaches 49.87%.
In addition, on July 10, when Hoban increased its stake to 20.15%, the board of directors of Jungseok Inha Educational Foundation under Hanjin Group resolved to purchase Hanjin KAL shares. They disposed of all previously held Korean Air shares to secure 73.6 billion won, and by adding additional funds, they decided to purchase Hanjin KAL shares worth a total of 102.3 billion won by the end of the year. This measure is difficult to view as a coincidence and is interpreted as Hanjin KAL preparing a defense strategy in anticipation of Hoban's movements.
Are they unable to buy, or choosing not to buy... Hoban's internal situation
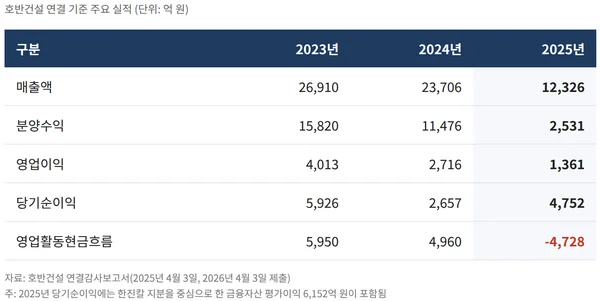
Hoban Construction, which plays a major role in this matter, had consolidated revenue of 1.2326 trillion won in 2025, a 48% decrease compared to the previous year. Operating profit also decreased by nearly half to 136.1 billion won, largely due to the impact of sales revenue plummeting 78% from 1.1476 trillion won to 253.1 billion won. Consolidated operating profit also shrank to one-third of its 2023 level of 401.3 billion won within two years. In other words, on the surface, the physical strength of Hoban's core business is not in good condition.
On the other hand, net profit increased by 78.9% to 475.2 billion won. This is a result of reflecting 615.2 billion won in valuation gains on financial assets, such as the Hanjin KAL stake. In fact, the book value of the Hanjin KAL stake has increased significantly from 900.8 billion won to 1.5544 trillion won over the past year.
In this situation, two interpretations are emerging in the market. First, there is an opinion that if one looks only at the financial statements, the capacity for additional purchases itself is low; second, there is a judgment that it is much more advantageous to remain as a simple investor and maintain valuation gains without making additional purchases. Considering that Hoban has shown steady interest in the aviation industry, such as participating in the Kumho Industrial acquisition race in 2015, some interpretations suggest that they are actually adjusting their speed strategically rather than due to limits in purchasing power.
To make matters worse, Taihan Cable & Solution, a core affiliate of Hoban Group, is also facing judicial risk as it recently came under prosecution investigation over allegations of leaking LS Cable & System's subsea cable technology. Due to these complex factors, Hoban stands at a critical crossroads: is it a "situation where they cannot buy more" due to a lack of additional purchasing capacity, or is it "not buying more" based on accounting benefits and strategic judgment?
The second act of the Hanjin KAL management dispute: 'The 10.58% stake held by Korea Development Bank' is the variable
The watershed moment that could have a profound impact on the shareholding issues of the two companies is the 10.58% stake held by Korea Development Bank. On December 17, the merger between Korean Air and Asiana Airlines will be finalized, and the integrated Korean Air will officially launch. In an opinion submitted to the National Assembly Political Affairs Committee in June 2025, Korea Development Bank stated that it would review ways to recover its investment considering the market situation after the merger.
Many in the market believe that since the aviation industry is a national industry, there is a high possibility that Korea Development Bank will lend its strength to Chairman Cho's side due to its policy-driven nature.
As such, there are many scenarios in the market that could overturn the management control issues of Hanjin KAL and Hoban. The moment Hoban's purpose shifts from simple investment to management control, it could act as a positive factor for the stock price. On the other hand, if the Korea Development Bank stake clearly sides with the Hanjin KAL side, it could act as a negative factor for the stock price due to the disappearance of momentum. Shareholders' interest is growing as to whether the shareholding issues between Hanjin KAL and Hoban will proceed to the second act of the dispute.
Comments 0
Comments are currently disabled.